
Naples flood insurance guide: Protecting Your Home on the Gulf Coast
Living in Naples means enjoying beautiful Gulf Coast views-but it also means accepting serious flood risk. Standard homeowners insurance won’t cover flood damage, leaving your property vulnerable when storms hit.
At Responsive Insurance, Inc., we’ve created this Naples flood insurance guide to help you understand your coverage options and protect what matters most. The right flood policy can be the difference between financial security and devastating loss.
Why Flood Insurance Matters in Naples
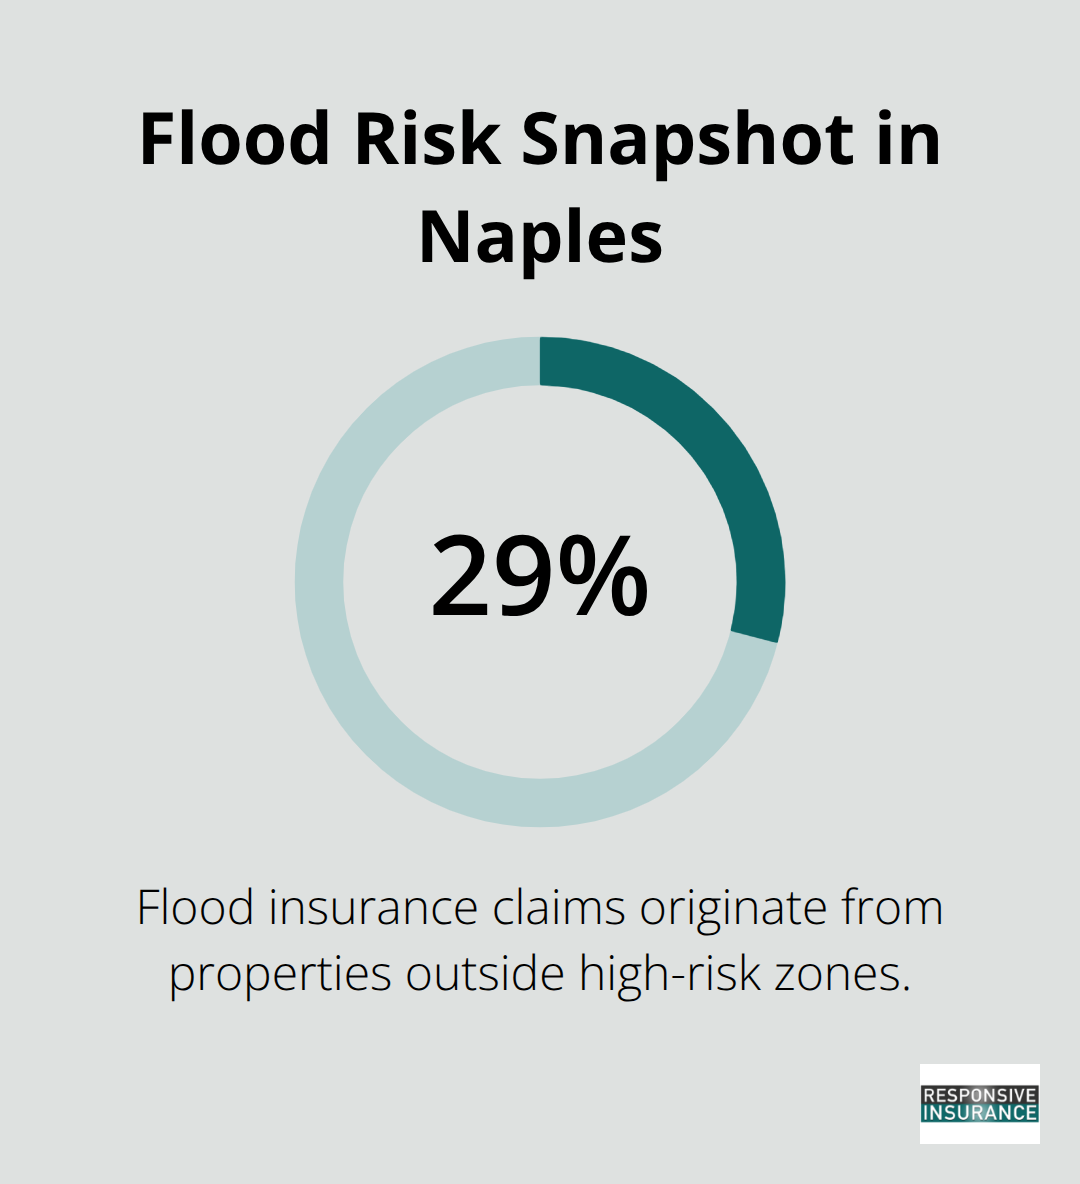
Flood damage strikes fast and costs serious money. About 29% of flood insurance claims come from properties outside high-risk flood zones, which means your home faces vulnerability even if you believe you’re safe. In Southwest Florida, flooding originates from multiple sources-heavy rains, poor drainage, and storm surge from the Gulf all create real threats. Over a 30-year mortgage in a high-risk area, you face at least a 1-in-4 chance of experiencing a flood, according to FEMA.
Naples sits on the Gulf Coast, which makes elevation and proximity to water major risk factors. The average NFIP flood insurance policy in Florida costs about $938 per year, but claims regularly exceed $25,000 when water damage strikes. Your standard homeowners insurance will not pay a single dollar for flood losses-this is the hard reality that catches most homeowners off guard. When water enters your home, you become responsible for the full cost unless you have a separate flood policy in place.
Standard Homeowners Insurance Has a Critical Gap
Your homeowners policy covers wind, hail, theft, and fire, but it explicitly excludes flood damage. If a heavy rainstorm overwhelms local drainage systems, a burst levee floods your neighborhood, or storm surge pushes water through your doors and windows, you pay everything out of pocket. Government disaster aid is not automatic and only becomes available after a Presidential declaration-and even then, assistance typically arrives as a loan you must repay, not a grant. If your property sits in a Special Flood Hazard Area and you have a federally backed mortgage or FDIC-insured loan, flood insurance becomes mandatory, not optional.
Coverage Limits and Policy Costs
The NFIP currently limits dwelling coverage to $250,000 and contents coverage to $100,000, which may not fully rebuild a damaged home in Naples where construction costs run high. Private flood insurance can offer higher limits-up to $500,000 or more for the dwelling and $250,000 for contents-but availability and pricing vary by insurer. The 30-day waiting period between purchase and coverage activation means you cannot buy a policy the day before a storm and expect protection. Flood insurance stands as a separate policy apart from your homeowners coverage, requiring its own application, premium, and deductible.
Understanding Your Coverage Options
The differences between NFIP and private policies matter significantly for Naples homeowners. NFIP policies provide standardized coverage with set limits, while private insurers typically offer more flexible options and higher dwelling limits. Your choice depends on your property’s flood zone, elevation, proximity to the Gulf, and how much coverage you actually need to rebuild. As you evaluate these options, understanding your specific flood risk becomes the next critical step in selecting the right protection for your home.
Your Two Flood Insurance Paths
NFIP vs. Private Coverage: Understanding Your Options
Naples homeowners face two distinct routes for flood protection: the National Flood Insurance Program administered by FEMA or private flood insurance from commercial carriers. The NFIP has dominated the market for decades, offering standardized coverage with fixed limits and pricing based on flood zone designation. Under NFIP rules, dwelling coverage maxes out at $250,000 and contents at $100,000, which creates a real problem in Naples where home values and reconstruction costs often exceed these thresholds. Private flood insurance emerged as a serious alternative after Congress reauthorized the NFIP in 2012 and encouraged private market growth.
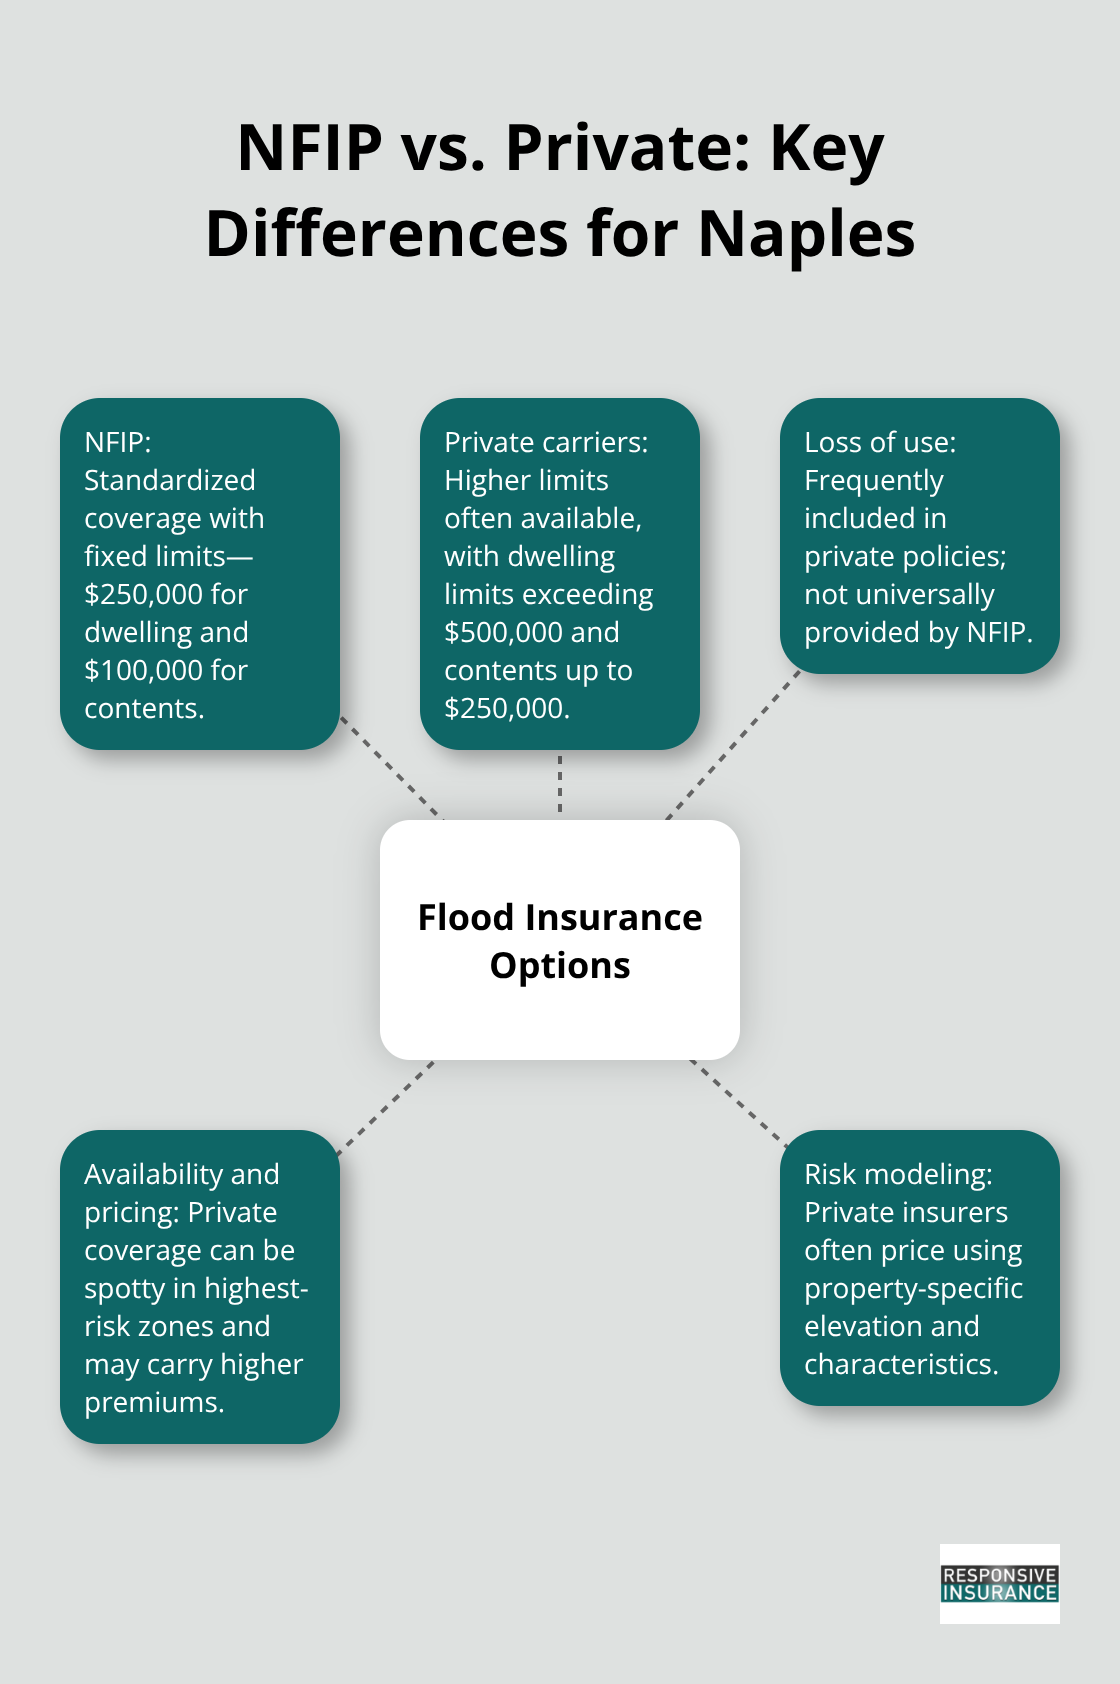
Today, private carriers offer dwelling limits exceeding $500,000 and contents coverage up to $250,000, making them attractive for higher-value properties.
Private policies also frequently include loss of use coverage that pays for temporary housing, meals, and related expenses if your home becomes uninhabitable-a benefit the NFIP does not universally provide. The tradeoff is availability: private flood insurance remains spotty in some areas and may carry higher premiums for properties in the highest-risk zones.
How Flood Zone Location Affects Your Costs
Your flood zone location dramatically shapes which option makes financial sense. NFIP pricing under Risk Rating 2.0, fully implemented as of April 1, 2023, now aligns premiums much closer to actual flood risk rather than broad zone classifications. In high-risk coastal zones near the Gulf, NFIP premiums can run $2,000 to $2,500 annually, while private carriers sometimes offer competitive rates through advanced risk modeling that accounts for your specific elevation and property characteristics. For properties in moderate-risk zones, the average NFIP policy costs roughly $938 per year statewide, though Naples properties typically run higher due to coastal exposure.
Elevation Certificates and Premium Reductions
An elevation certificate-which documents your home’s lowest floor height and costs between $400 and $750-can unlock meaningful premium reductions from both NFIP and private insurers because it proves your actual risk exposure. Naples sits in Community Rating System Class 5, which qualifies residents for up to a 25 percent discount on standard NFIP policies if you purchase through the program.
Getting the Right Quote for Your Situation
Comparing quotes from both NFIP and multiple private carriers reveals which path delivers the coverage limits you actually need at a price that fits your budget. An independent insurance agent can help you navigate both markets and identify which carrier offers the best combination of coverage, limits, and cost for your specific property. The right choice depends on your home’s value, your flood zone designation, and how much protection you want beyond the NFIP’s standard limits.
Choosing the Right Flood Policy for Your Naples Home
Identify Your Flood Zone First
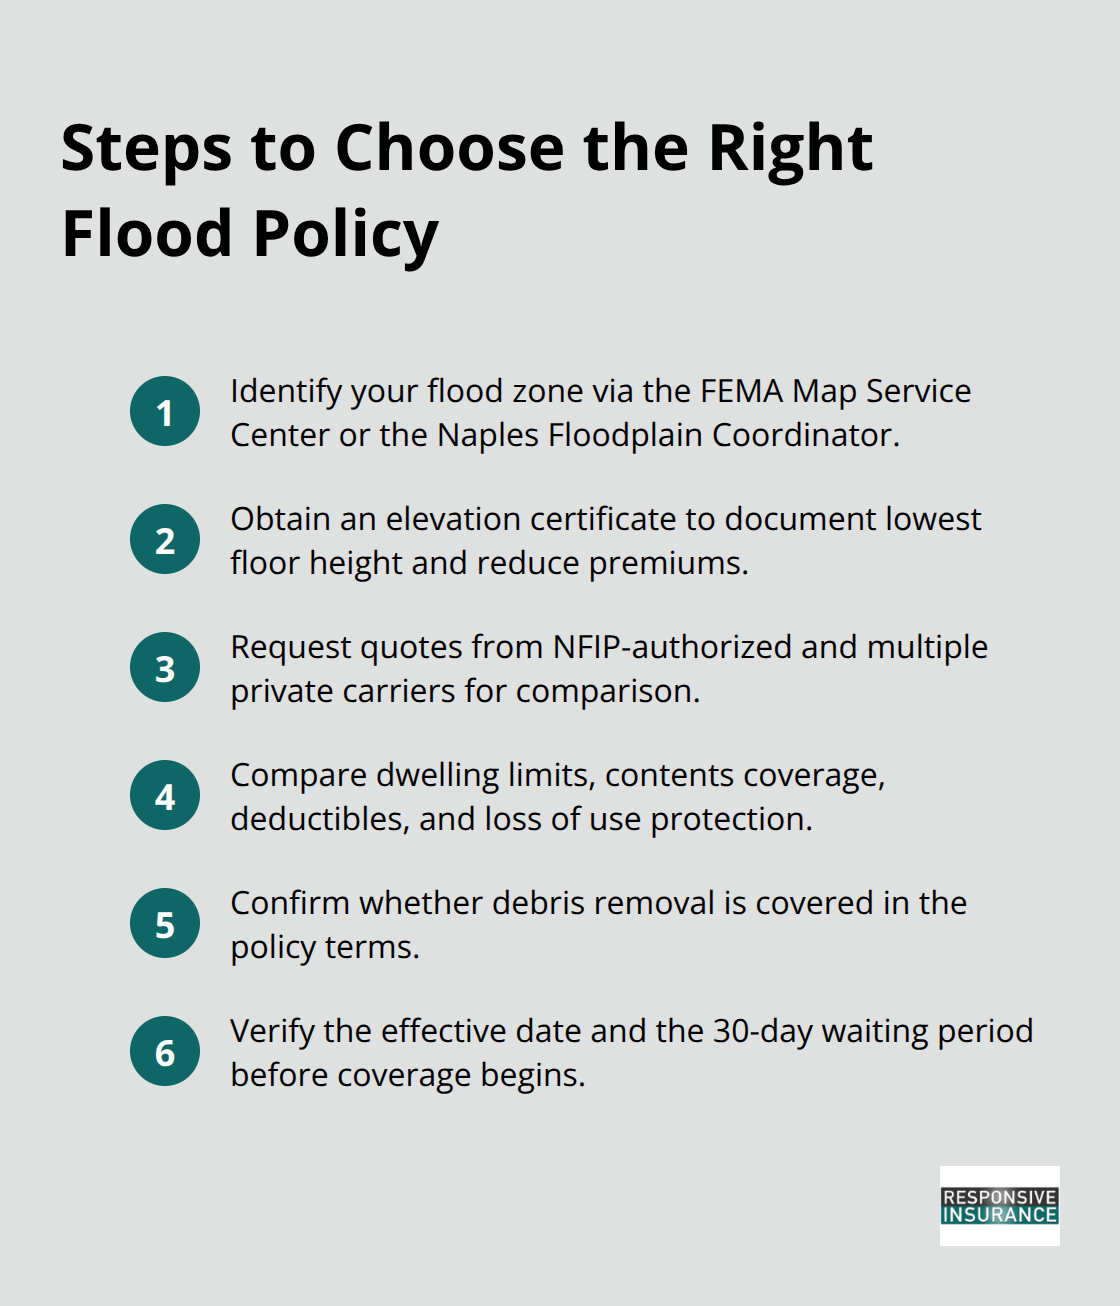
Start with your flood zone before you compare a single quote. Visit the FEMA Flood Map Service Center or contact the Naples Floodplain Coordinator at 239-213-5039 to identify whether your property sits in a Special Flood Hazard Area, which carries the highest premiums and mandatory insurance if you have a federally backed mortgage. Properties in Zone V or VE near the Gulf typically cost around $2,413 annually through NFIP, while Zone X properties average roughly $637 per year. Once you know your zone, obtain an elevation certificate if you don’t already have one-this $400 to $750 investment documents your home’s lowest floor height and often reduces premiums significantly because it proves your actual risk rather than relying on broad zone assumptions.
Leverage Local Discounts and Risk Assessments
Naples qualifies for Community Rating System Class 5, which delivers flood insurance premium discounts ranging from 5% to 45%, so ask your agent whether your property qualifies. Private insurers use advanced risk modeling that sometimes offers better rates than NFIP in moderate-risk zones, particularly if your home sits on elevated land or sits back from the coast. The difference between NFIP and private pricing can be substantial-private carriers sometimes undercut NFIP significantly once your elevation and specific property characteristics are factored in, especially for homes valued above $300,000 where NFIP’s $250,000 dwelling limit creates a real coverage gap.
Compare Multiple Quotes and Coverage Details
Quotes from at least three carriers matter because flood insurance pricing varies wildly depending on underwriting methodology and risk assessment. Request quotes from both an NFIP-authorized carrier and two to three private flood insurers, then compare dwelling limits, contents coverage, deductibles, and whether loss of use coverage is included. Ask specifically whether the policy covers debris removal, which standard NFIP policies include but some private carriers carve out. Check the effective date and confirm the 30-day waiting period-if a storm threatens in six weeks, you need to act now, not later.
Work with an Independent Agent
An independent insurance agent in Naples who works with multiple carriers can pull quotes faster than contacting insurers individually and can explain the nuances between policies that online comparison tools miss. As an independent agency based in Naples, we work with numerous A-rated carriers to compare your options and find the coverage that matches both your property’s actual risk and your budget constraints. Don’t assume NFIP is cheaper-private carriers sometimes undercut NFIP significantly once your elevation and specific property characteristics are factored in, especially for homes valued above $300,000 where NFIP’s $250,000 dwelling limit creates a real coverage gap.
Final Thoughts
Flood damage in Naples strikes fast, costs serious money, and affects properties both inside and outside high-risk zones. Your standard homeowners policy will not cover a single dollar of flood losses, which means you bear the entire financial burden unless you carry a separate flood insurance policy. About 29 percent of NFIP flood claims originate from properties outside Special Flood Hazard Areas, and claims regularly exceed $25,000 when water enters your home.
You have real options to protect yourself. The National Flood Insurance Program offers standardized coverage with dwelling limits up to $250,000, while private flood insurers frequently provide higher limits and more flexible coverage terms. Naples qualifies for Community Rating System Class 5, which delivers discounts up to 25 percent on NFIP policies, and an elevation certificate ($400 to $750) often reduces premiums significantly by documenting your actual risk exposure rather than relying on broad zone assumptions.
Start by identifying your flood zone through the FEMA Flood Map Service Center or by calling the Naples Floodplain Coordinator at 239-213-5039. Then obtain quotes from both NFIP-authorized carriers and multiple private insurers to compare dwelling limits, contents coverage, deductibles, and loss of use protection. We at Responsive Insurance, Inc. work with multiple A-rated carriers to help Naples homeowners find flood coverage that matches their property’s actual risk and budget, so contact us to compare your options and secure the protection your home needs on the Gulf Coast.


