
Naples Condo Insurance Florida: What Condo Owners Should Know
Condo ownership in Naples comes with unique insurance challenges that many owners overlook. Your condo association’s master policy covers common areas, but it leaves significant gaps in protection for your individual unit and belongings.
At Responsive Insurance, Inc., we’ve helped countless Naples condo owners understand why Naples condo insurance Florida requires a personalized approach. This guide walks you through the coverage you actually need and how to avoid costly mistakes.
Why Condo Insurance Works Differently Than Home Insurance
HO-6 condo insurance exists because a standard homeowners policy (HO-3) doesn’t fit how condo ownership actually works. Your condo association’s master policy handles the building structure and common areas like hallways, roofs, and exterior walls. Your individual HO-6 policy protects what the master policy doesn’t: your unit’s interior, your personal belongings, your liability exposure, and your living costs if your unit becomes uninhabitable.
Understanding Your Master Policy Type
The National Association of Insurance Commissioners notes that Florida condo master policies come in two types-All-In policies that cover more of the structure, or Bare-Walls policies that cover only the exterior and common areas.
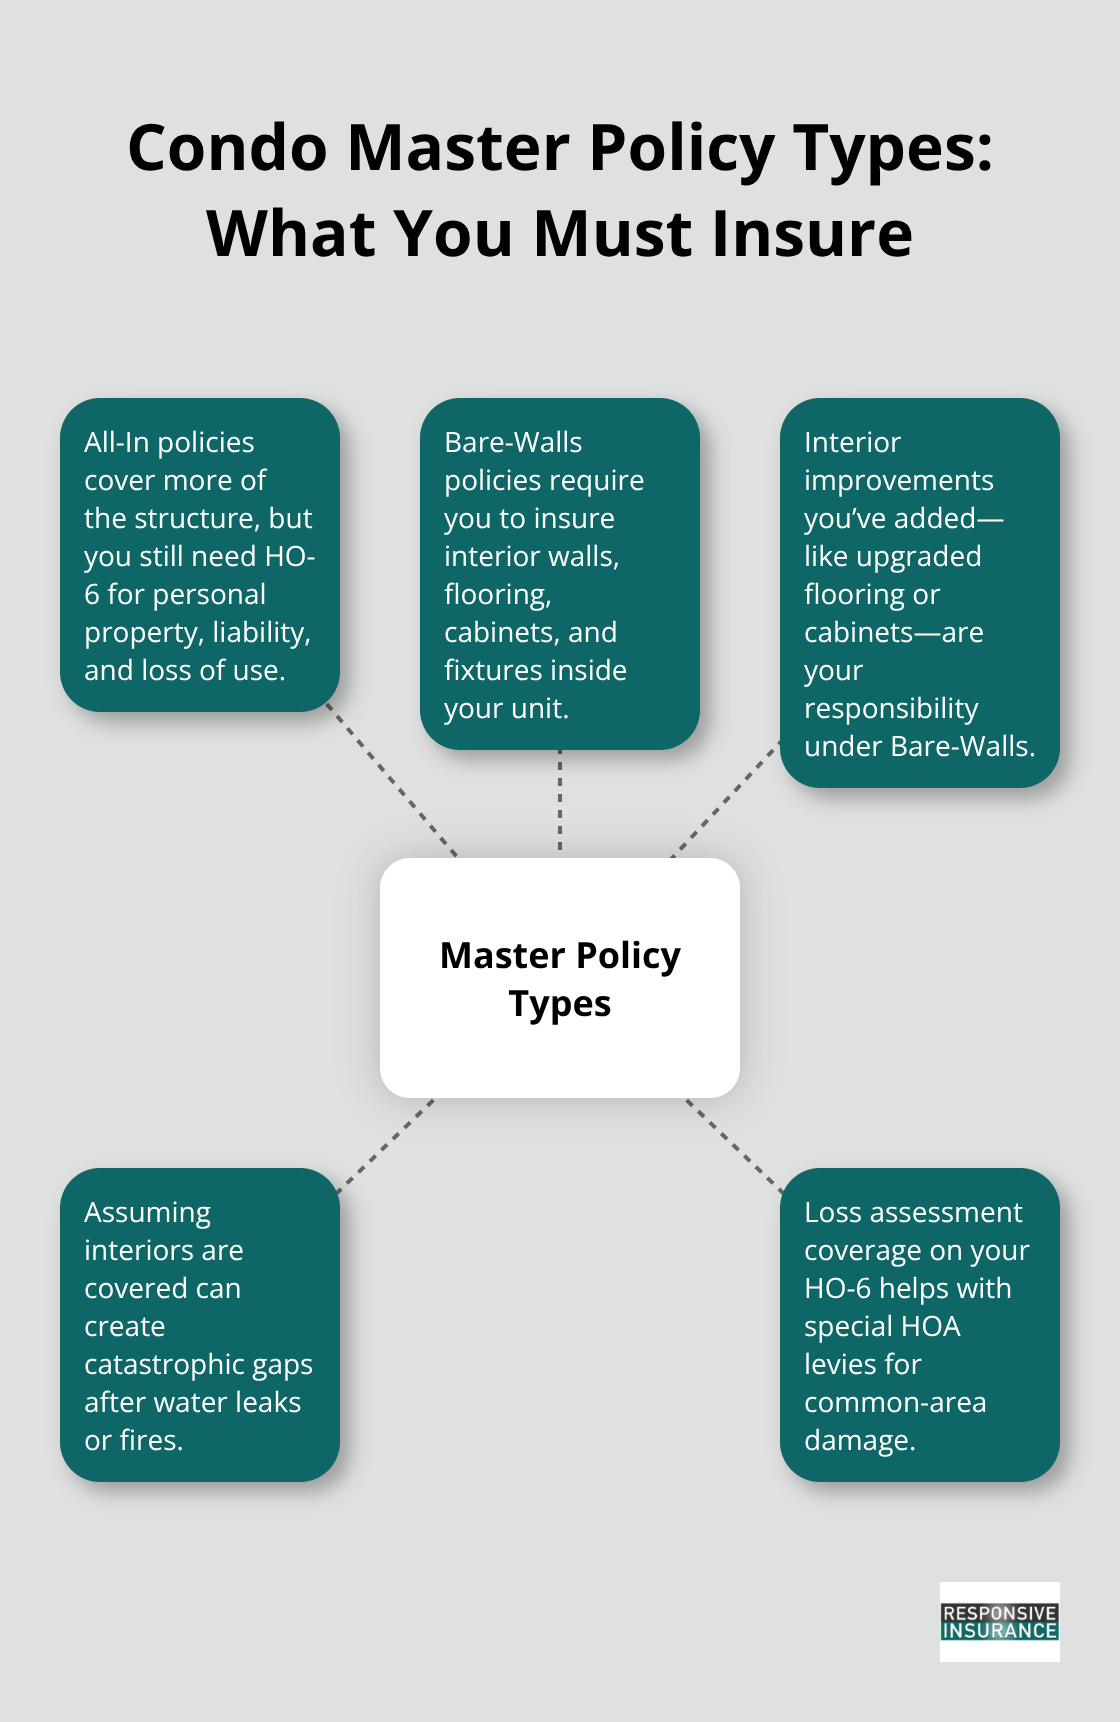
If your association has a Bare-Walls policy, you must insure interior walls, flooring, and any improvements you’ve made inside your unit. This distinction matters enormously. A Naples condo owner who assumes the master policy covers everything inside their unit can face a catastrophic gap when a water leak damages interior walls or a fire destroys kitchen cabinets. The Insurance Information Institute emphasizes that without HO-6 coverage, you have no protection for these interior elements or personal property.
Calculate Your Dwelling Coverage Limit
Your dwelling coverage limit should reflect what it would cost to rebuild your interior from the studs outward. Many Naples condo owners make the mistake of using a generic number or matching their neighbor’s limit. Instead, obtain a contractor’s estimate for your specific unit-account for your finishes, square footage, and any upgrades you’ve installed. Personal property coverage should be 50 to 70 percent of your dwelling limit according to the Insurance Information Institute, with replacement-cost protection rather than actual cash value so depreciation doesn’t reduce your reimbursement.
Account for Liability and Deductible Exposure
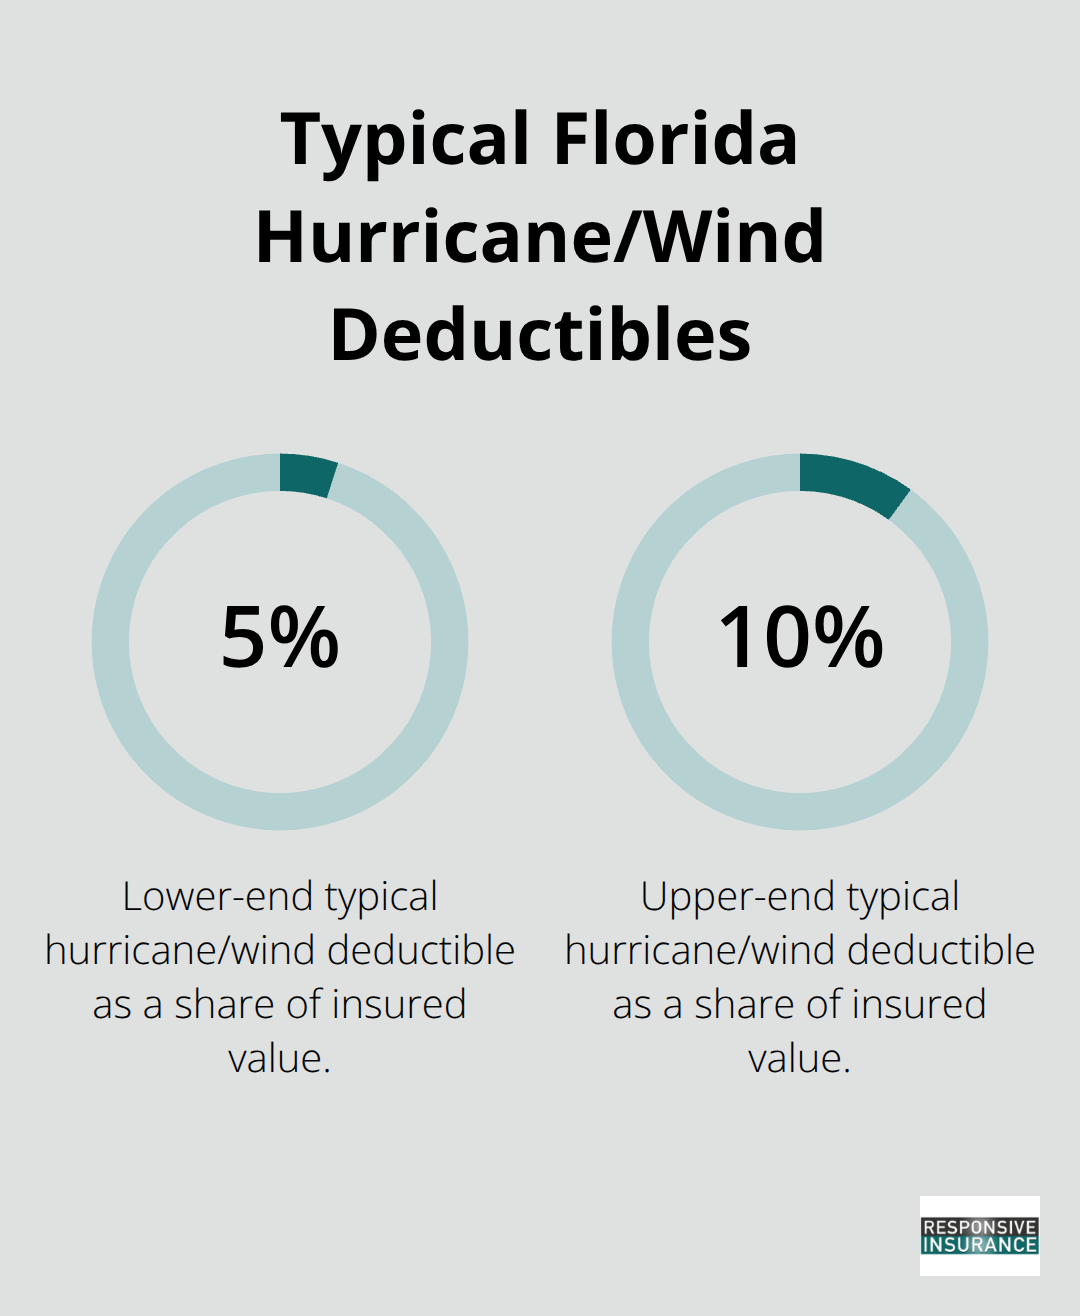
Liability coverage of $300,000 to $500,000 is commonly recommended, depending on your assets and exposure. Florida’s separate hurricane and windstorm deductibles typically range from 5 to 10 percent of insured value according to the Florida Office of Insurance Regulation, which can mean thousands in out-of-pocket costs after a claim. Loss assessment coverage protects you against special HOA levies when common areas suffer damage; at least $50,000 is standard guidance. Without loss assessment coverage, the association could bill you directly for repairs to shared spaces, bypassing insurance entirely.
Compare Quotes Against Your Specific Needs
This is why comparing your specific unit’s needs against a cookie-cutter policy is non-negotiable. The next section walks you through the coverage gaps that catch many Naples condo owners off guard-and how to spot them before they cost you money.
Coverage Gaps That Drain Naples Condo Owners’ Bank Accounts
Most Naples condo owners face their coverage shortfalls the hard way-after a loss strikes. Three major gaps expose owners to financial disaster, and spotting them now prevents costly mistakes later.
Personal Property Coverage Falls Short of What You Own
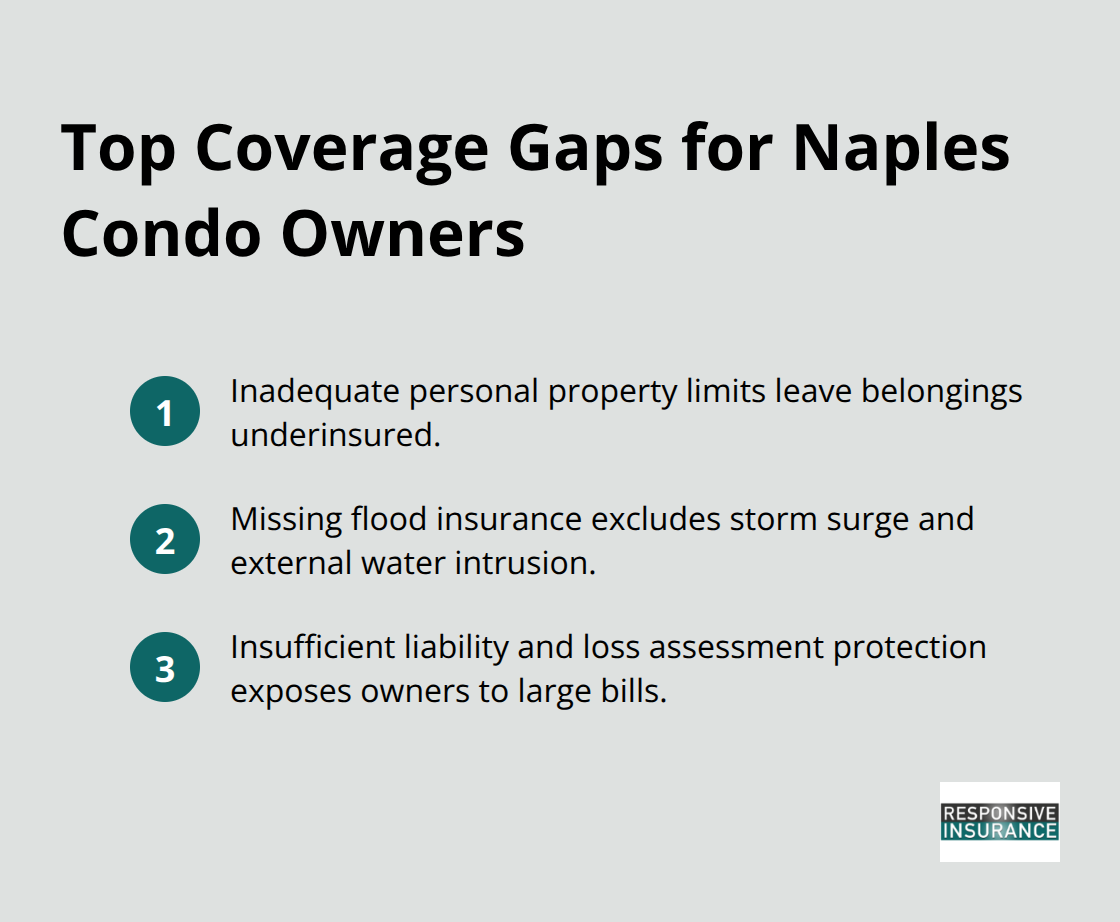
Personal property coverage represents the first gap that catches owners off guard. Personal property coverage falls short of what you own, with most policies providing coverage at about 50 to 70 percent of your dwelling limit. A Naples condo with a $100,000 dwelling limit should carry $50,000 to $70,000 in personal property coverage. If you own jewelry, art, electronics, or collectibles, standard personal property coverage caps these items at $2,500 total according to industry guidelines. A single engagement ring or art collection exceeds that limit instantly. You need to inventory your belongings and compare that total against your policy limit. If the gap exists, add a Jewelry & Other Valuables endorsement to protect high-value items beyond standard limits.
Flood Damage Leaves You Exposed in a High-Risk Zone
The second gap hits when water damage occurs. Standard HO-6 policies cover sudden internal leaks from burst pipes or failed appliances, but they do not cover flood damage from external sources like storm surge, heavy rain runoff, or rising water tables. Naples sits in a high-hurricane and flood-risk zone according to the Insurance Information Institute, yet many condo owners skip flood insurance entirely because they assume it is not necessary. The National Flood Insurance Program and private flood insurers operate separately from your HO-6 policy. If a tropical storm dumps eight inches of rain and water enters your unit from outside, your standard condo policy pays nothing. Your deductible for flood insurance also applies independently, meaning you face two separate out-of-pocket costs in a single event. Water Backup/Overflow endorsements cover costly damage from backed-up drains or pipes, but they do not replace flood insurance for external water intrusion.
Liability and Assessment Gaps Create Hidden Financial Exposure
Liability exposure creates a third blind spot that owners ignore at their peril. Your HO-6 policy covers your personal liability for injuries that happen inside your unit, but the condo association’s master policy protects common areas. If a guest slips on your kitchen floor and sues you for $250,000 in medical bills and lost wages, your liability coverage must cover that claim. Standard HO-6 liability limits of $100,000 are dangerously low for most Naples owners. The Insurance Information Institute recommends $300,000 to $500,000 depending on your assets. Additionally, loss assessment coverage protects you when the HOA faces a special levy for damage to common areas. If the building’s roof sustains hurricane damage and the master policy deductible is $50,000, the association can bill unit owners directly for that deductible through a special assessment. Without loss assessment coverage of at least $50,000, you absorb that cost personally. Many condo owners carry no loss assessment coverage at all, exposing themselves to assessments that can reach $10,000 or more per unit after a major event.
These three gaps-inadequate personal property limits, missing flood coverage, and insufficient liability protection-form the foundation of what your policy must address. The next section shows you exactly how to evaluate your condo association’s master policy and determine what coverage limits your specific unit actually needs.
Securing the Right Coverage Limits for Your Naples Condo
Request Your Master Policy Details
Start by obtaining a copy of your condo association’s master policy directly from your HOA board or management company. Request the declarations page, which shows what the master policy actually covers and what it does not. Call your association’s management office and ask three specific questions: Is the master policy All-In or Bare-Walls? What is the master policy deductible for wind and hurricane damage? Does the master policy include loss assessment coverage for unit owners? The answers to these questions determine your HO-6 coverage requirements.
If your association has a Bare-Walls policy, you must carry enough dwelling coverage to rebuild your interior walls, flooring, cabinets, and fixtures from scratch. If the master policy deductible is $50,000 for wind damage, you need at least $50,000 in loss assessment coverage to protect yourself from a special HOA bill. Many Naples condo owners skip this step entirely and simply buy whatever limits the insurance agent suggests, which often leaves them underinsured or overpaying for coverage the master policy already provides.
Get Contractor Estimates for Your Specific Unit
Obtain two contractor estimates for your specific unit’s interior replacement cost. Do not use an online calculator or generic square-footage estimate. Contact local contractors in Naples and request estimates that account for your finishes, upgrades, and current construction costs in Southwest Florida. One estimate should reflect replacing everything to original condition; the second should reflect replacing with comparable quality.
Personal property coverage should be set at 50 to 70 percent of your dwelling limit, with replacement-cost protection rather than actual cash value. If your dwelling coverage is $150,000, your personal property should be $75,000 to $105,000. Inventory your belongings, especially high-value items like jewelry, art, or electronics. Standard policies cap jewelry at $2,500 total, so a Jewelry & Other Valuables endorsement is essential if you own items exceeding that threshold.
Compare Quotes From Multiple A-Rated Insurers
Request quotes from three A-rated insurers and compare their specific rates, deductible options, and available endorsements like Water Backup/Overflow coverage and Hurricane Screen Enclosure protection. Do not choose based on price alone. A policy $200 cheaper annually may exclude critical endorsements or carry a $5,000 hurricane deductible instead of $2,500, costing you thousands more when a claim occurs.
As an independent agency based in Naples, we work with multiple A-rated carriers to compare these exact details so you get appropriate coverage at a fair price rather than settling for the lowest quote. Your liability coverage should reach $300,000 to $500,000 depending on your assets and exposure. Florida’s separate hurricane and windstorm deductibles typically range from 5 to 10 percent of insured value according to the Florida Office of Insurance Regulation, which can mean thousands in out-of-pocket costs after a claim.
Loss assessment coverage is an optional protection you can add to help pay for special assessment fees when common areas suffer damage.
Final Thoughts
Naples condo insurance Florida protects what your association’s master policy leaves uncovered, and getting it right prevents financial disaster when a loss strikes. The three coverage gaps we covered-inadequate personal property limits, missing flood insurance, and insufficient liability protection-account for most claims disputes and out-of-pocket costs that Naples condo owners face after hurricanes, water damage, or accidents. Your action plan starts with requesting your master policy details from your HOA to confirm whether it is All-In or Bare-Walls coverage, then obtaining contractor estimates for your specific unit’s interior replacement cost rather than guessing at a dwelling limit.
Next, inventory your belongings and compare that total against your personal property coverage, adding a Jewelry & Other Valuables endorsement if you own high-value items. Verify your liability coverage reaches $300,000 to $500,000 depending on your assets, and confirm you carry at least $50,000 in loss assessment coverage to protect against special HOA levies. Florida’s hurricane and windstorm exposure makes adequate coverage non-negotiable, since a single tropical storm can trigger thousands in out-of-pocket costs if your deductibles are too high or your coverage limits are too low.
We at Responsive Insurance, Inc. work with multiple A-rated carriers to compare coverage options and find the right fit for your specific unit. Contact us today for a personalized condo insurance quote that addresses your actual needs and protects your Naples condo investment.


