
Naples Homeowners Insurance Options: Find Your Best Coverage
Finding the right Naples homeowners insurance options takes more than just picking the cheapest quote. Your home is likely your biggest investment, and the coverage you select directly impacts your financial security when storms, theft, or accidents happen.
We at Responsive Insurance, Inc. created this guide to help you understand what coverage types matter most, what factors affect your rates, and how to compare policies side by side. By the end, you’ll know exactly which protection levels work for your situation.
What Coverage Types Actually Protect Your Naples Home
Dwelling Coverage Forms Your Foundation
Dwelling coverage forms the foundation of any homeowners policy in Naples, and it’s where most people get confused. This coverage pays to repair or rebuild your home’s structure if fire, wind, theft, or vandalism damages it. The critical detail here is that dwelling coverage only protects the building itself-not your belongings inside. For a $600,000 home in Naples, dwelling coverage typically costs between $851 and $4,193 annually depending on your chosen limit, according to Policygenius. Older homes with aged roofs push toward the higher end because they cost more to rebuild and face greater weather risk.
You need to know your home’s actual replacement cost, not its market value. Many Naples homeowners underestimate this figure, then face serious out-of-pocket expenses after a loss. A 4-point inspection costs roughly $175 but reveals structural issues that affect your quote and eligibility for better rates. Wind mitigation inspections, also around $175, often qualify you for discounts if your roof meets current standards. These inspections aren’t optional-they’re practically required in Naples if you want competitive pricing.
Personal Property Coverage Protects Your Belongings
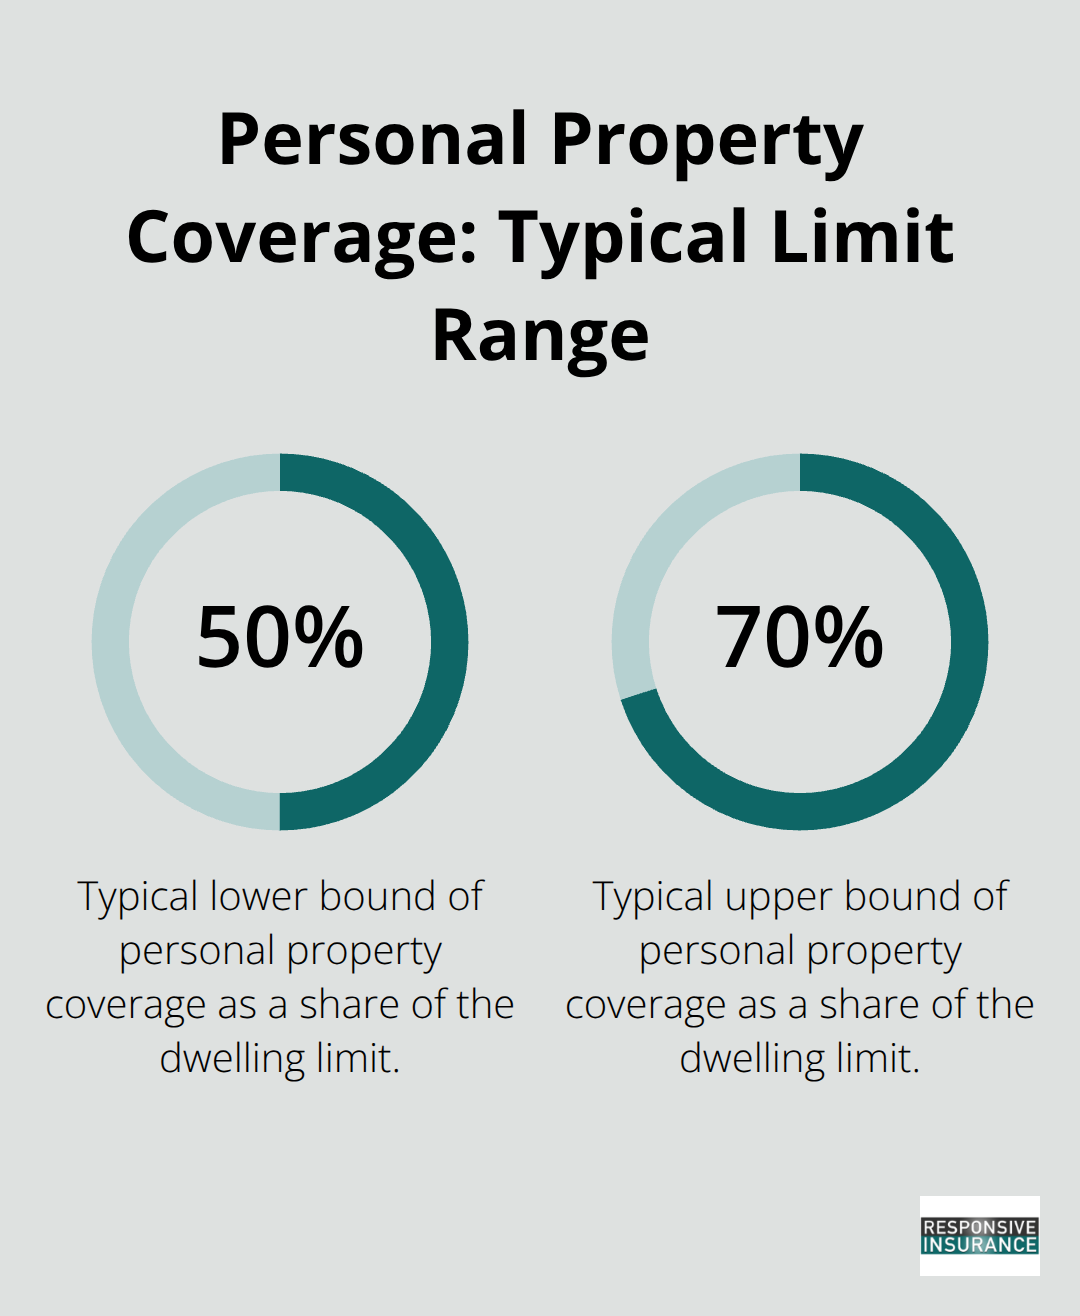
Your clothes, furniture, electronics, and jewelry aren’t covered by dwelling coverage alone. Personal property coverage protects these items up to a percentage of your dwelling limit, typically 50-70%.
The valuation method matters enormously here. Replacement Cost coverage pays what it costs to replace items new, while Actual Cash Value coverage pays what your items are worth today after depreciation. Replacement Cost costs more but protects you better-if your five-year-old television burns in a fire, Replacement Cost covers a new TV, while Actual Cash Value covers only its depreciated value.
Documentation makes all the difference before loss happens. Create a home inventory with photos, receipts, and serial numbers organized by room, which dramatically speeds claims and prevents you from underestimating your belongings’ value. This step takes a few hours but saves thousands when you file a claim.
Liability and Medical Payments Coverage Protect You Financially
Liability coverage protects you financially if someone gets injured on your property and sues. Medical payments coverage handles small injuries without requiring a lawsuit. These aren’t luxuries in Naples (with property values high and litigation common in Florida, liability claims can reach six figures quickly). Most policies offer $100,000 to $300,000 in liability protection, though you should consider higher limits given your home’s value.
The right coverage combination depends on your specific home, location, and risk tolerance. Understanding these three core protection types positions you to make informed decisions when comparing policies from different carriers.
What Drives Your Naples Insurance Costs
Home Age, Roof Condition, and Construction Materials Shape Your Premium
Your home’s age, size, and construction materials directly determine your insurance premium, and Naples insurers scrutinize these factors heavily. A roof under 15 years old qualifies for lower rates, while homes built after 2005 receive better pricing because they meet current building codes and weather-resistant standards. According to Policygenius, dwelling coverage for a $600,000 home ranges from $851 annually for minimal coverage to $4,193 for full replacement protection, but homes with aged roofs often land in the $3,000–$4,000 range. Insurers factor in higher replacement costs and greater storm vulnerability when roofs age. Roof material matters significantly-metal or impact-resistant shingles cost more upfront but earn you wind mitigation discounts that offset higher premiums. The size of your home affects the base premium, yet construction materials and structural condition drive the real cost differences.
If you own an older home, a 4-point inspection (roughly $175) immediately reveals which factors push your quotes higher. You can then prioritize repairs that yield the biggest premium reductions. This inspection identifies structural issues that affect your quote and eligibility for better rates.
Location and Flood Zone Status Amplify Your Costs
Location within Naples determines whether you pay $2,434 or $2,582 annually for identical coverage, depending on your ZIP code, according to Policygenius data. Proximity to the coast amplifies your costs because storm surge and hurricane wind risk represent genuine financial threats. Homes near water face substantially higher deductibles and may require separate windstorm coverage with a 2% deductible (roughly $12,000 on a $600,000 home). Flood zone status matters enormously; being in or near a Special Flood Hazard Area triggers flood insurance requirements and higher base premiums. Wind mitigation inspections, also around $175, often qualify you for discounts if your roof meets current standards.
Claims History and Credit Score Determine Your Rate Class
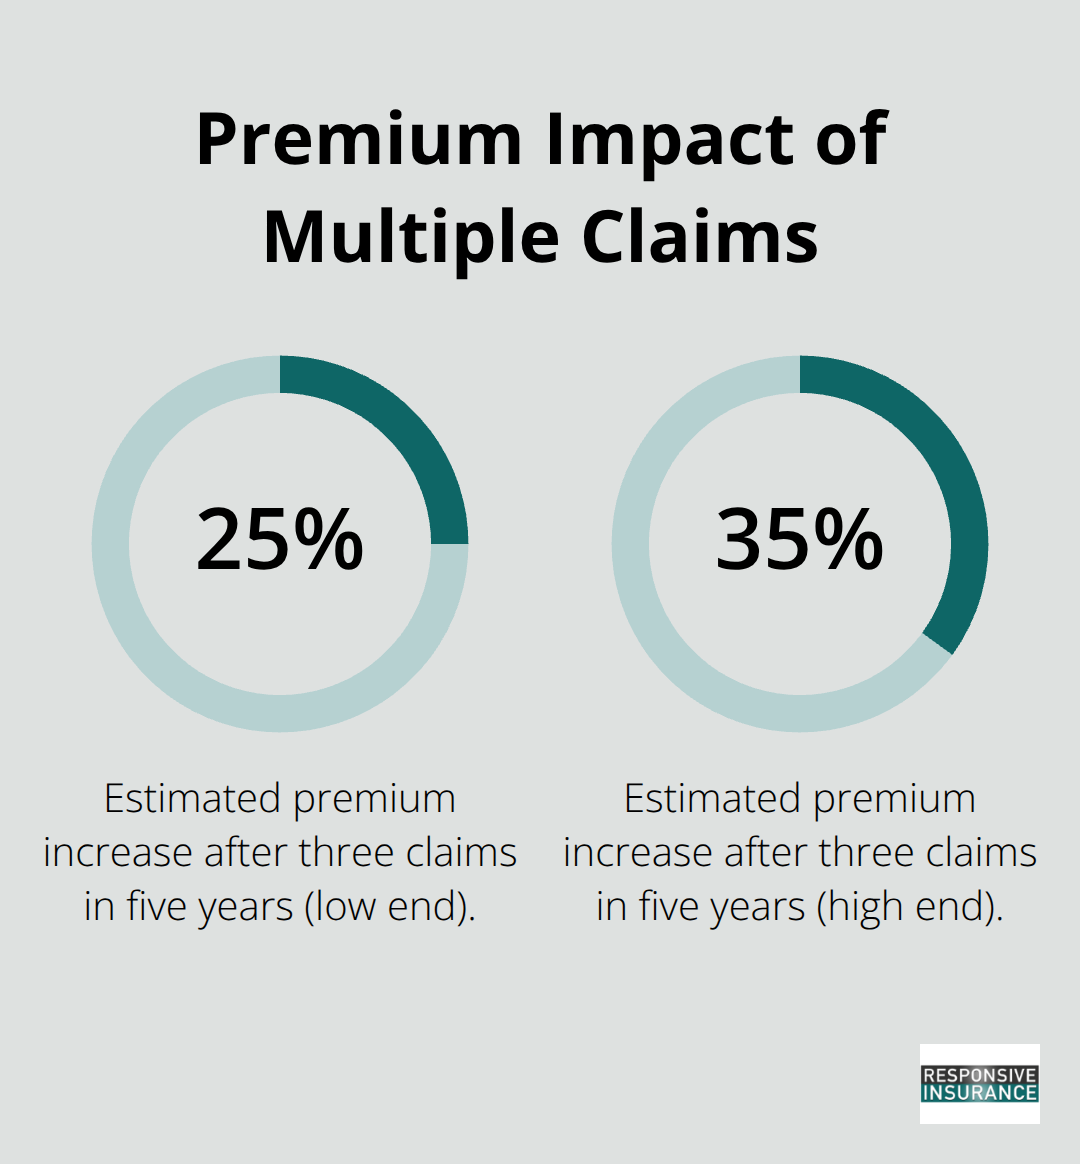
Your claims history and credit score work together to either reward or penalize you financially. Three claims in five years can increase your premium by 25–35% compared to a clean history, and poor credit signals higher risk to insurers. This pushes you toward costlier carriers like Citizens Property Insurance or limits you to specialized providers.
The good news is these factors are partially controllable-improving your roof before renewal, installing hurricane-resistant features, and maintaining clean credit all produce measurable savings. Understanding what insurers measure helps you identify which improvements deliver the fastest rate reductions before your next renewal.
How to Choose the Right Homeowners Policy in Naples
Calculate Your Home’s True Replacement Cost
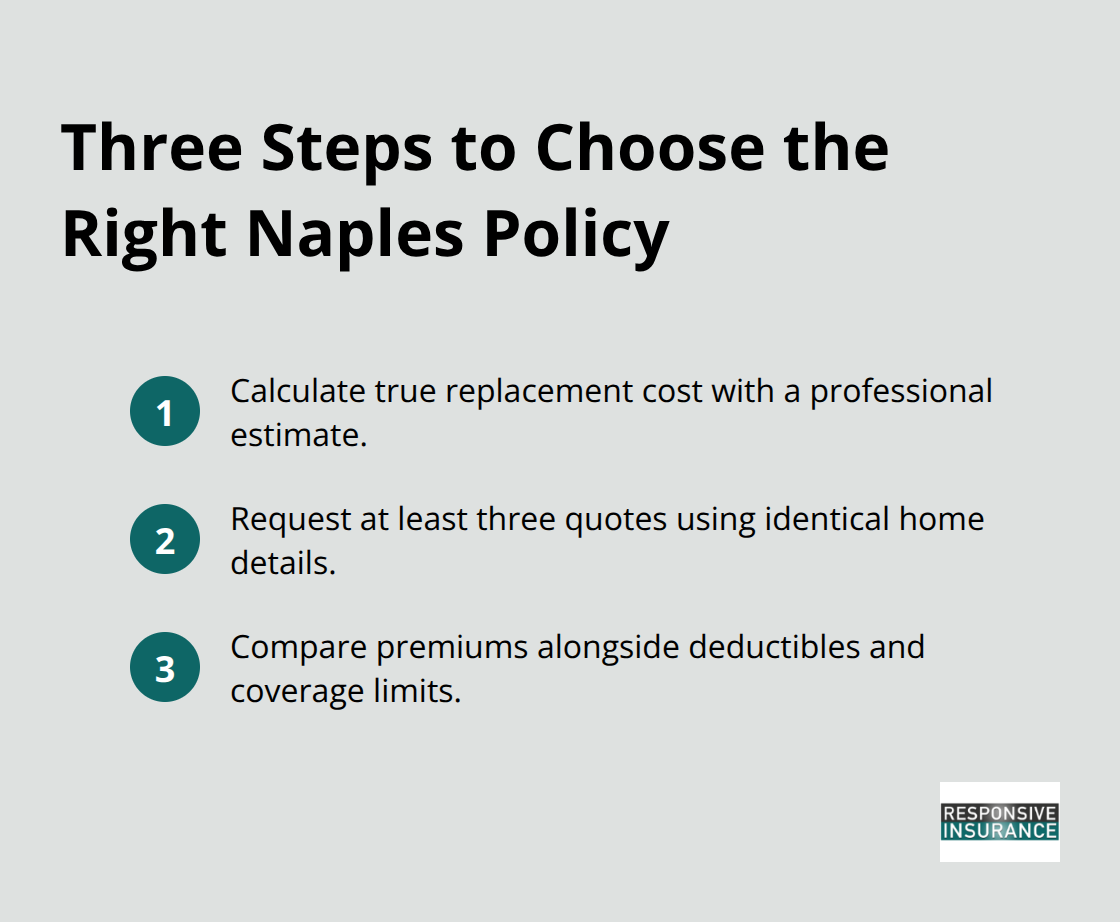
Your home’s replacement cost differs significantly from your purchase price or mortgage statement. The replacement cost reflects what it would actually cost to rebuild your home from scratch with current labor rates and materials, which typically runs 10–20% higher than your home’s market value in Naples. If you purchased your home for $600,000, rebuilding it might cost $680,000–$750,000 depending on lot location, construction quality, and current material prices. A Reconstruction Cost Estimate from a local contractor or appraiser costs $300–$500 but prevents you from underinsuring your property. Many Naples homeowners skip this step, then face massive gaps between their coverage limit and actual rebuild expenses after a total loss. Your dwelling coverage limit should match or slightly exceed this replacement cost figure. Once you know the real number, you can work backward to determine what deductible level keeps your monthly premium affordable without creating dangerous coverage gaps.
Compare Quotes from Multiple Carriers
Quotes from multiple carriers reveal how dramatically costs swing based on underwriting differences. Request quotes from at least three carriers and provide identical information to each: exact roof age, square footage, construction year, and desired coverage limits. Many Naples homeowners rely on realtor-provided insurance estimates during home searches, which are notoriously inaccurate and should never guide your actual purchasing decision.
Evaluate Deductible Options and Coverage Limits
After you gather quotes, compare not just the premium but the deductible options available. However, don’t sacrifice coverage to chase lower premiums-a cheap policy with inadequate dwelling or liability limits leaves you exposed to catastrophic financial loss. The goal is finding the carrier offering competitive rates while maintaining adequate protection for your actual home value and personal liability exposure in a state with active litigation.
Final Thoughts
Naples homeowners insurance options require you to balance three core protection types: dwelling coverage that rebuilds your structure, personal property coverage that replaces your belongings, and liability coverage that shields you from lawsuits. Each protection type serves a distinct purpose in your overall financial security, and the combination you select directly determines how much you’ll pay out of pocket after a loss. Your coverage choices must match your home’s actual replacement cost and your personal liability exposure in a state where litigation costs run high.
Start your policy search by calculating your home’s true replacement cost through a professional estimate rather than relying on purchase price or mortgage statements. Next, request quotes from at least three carriers using identical information about roof age, construction year, and desired coverage limits, then compare the deductibles and coverage limits each carrier offers alongside their premiums. This process takes a few hours but prevents you from overpaying or underinsuring your property when you need protection most.
A local agent at Responsive Insurance, Inc. compares coverage options across multiple A-rated insurance companies to find the best fit for your situation and handles the inspection coordination, windstorm deductible explanations, and flood coverage requirements that Naples homeowners face. They identify discounts you might miss on your own and advocate for you when claims arise, positioning you to make informed decisions about Naples homeowners insurance options rather than defaulting to the cheapest quote available.


