
Naples Business Insurance Options: Protecting Your Small Biz
Running a small business in Naples means facing unique risks-from hurricanes to liability claims that could threaten everything you’ve built.
At Responsive Insurance, Inc., we know that finding the right Naples business insurance options isn’t one-size-fits-all. This guide walks you through the coverage types that matter most, the specific threats your business faces, and how to choose a plan that actually fits your needs.
What Coverage Types Do Naples Small Businesses Actually Need?
General Liability Insurance Protects Against Lawsuits
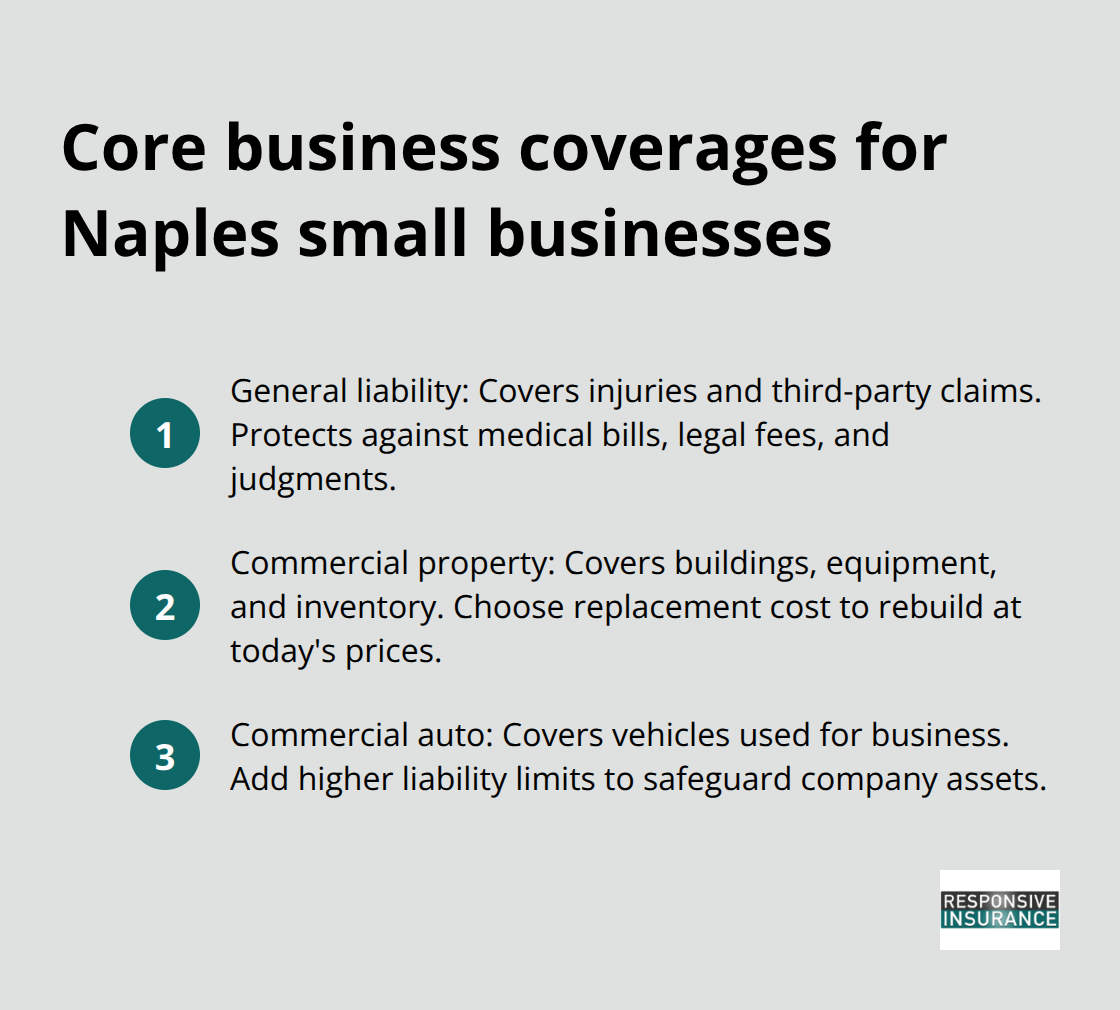
General liability insurance protects your business when someone gets injured on your property or claims your product caused them harm. In Naples, where tourism drives foot traffic through retail and service businesses, the risk of slip-and-fall claims or customer injuries remains particularly high. A general liability policy covers medical expenses, legal fees, and court judgments up to your policy limits. Most Naples small businesses should carry between $1 million and $2 million in general liability coverage, depending on their industry and customer volume. If you operate a restaurant, salon, or retail shop, this coverage becomes non-negotiable because customer interactions create constant exposure.
Commercial Property Insurance Covers Your Business Assets
Commercial property insurance protects your buildings, equipment, inventory, and fixtures from fire, theft, and weather damage. In Southwest Florida, hurricane damage represents your biggest threat. Your property policy should include replacement cost coverage rather than actual cash value, meaning the insurer pays what it costs to rebuild today, not what your ten-year-old equipment is worth. Naples business owners often underestimate their property values and end up underinsured; a thorough inventory of everything in your space (including furniture, technology, and stock) prevents this costly mistake. If you lease your building, your landlord’s insurance covers the structure, but you need your own policy for your belongings and improvements you’ve made to the space.
Commercial Auto Insurance Requires Separate Coverage
If your business owns or uses vehicles for work, personal auto insurance won’t cover business use. Commercial auto insurance covers company vehicles, employee-driven cars on business errands, and hired or non-owned vehicles your staff uses temporarily. Florida requires minimum liability coverage of $10,000 for property damage and $10,000 for bodily injury per person, but these limits are dangerously low-a single serious accident could bankrupt a small business. We recommend coverage limits of at least $100,000 per person and $300,000 per accident for Naples businesses with employees (this protects your company assets from claims). If your team makes deliveries, visits client sites, or transports products, commercial auto coverage protects you from claims that could otherwise threaten your business directly.
These three coverage types form the foundation of business protection in Naples, but your specific risks depend on your industry and operations. The next section walks you through the particular threats that small businesses in Southwest Florida face most often.
What Threatens Your Naples Business Most
Hurricane Season Demands Flood Insurance
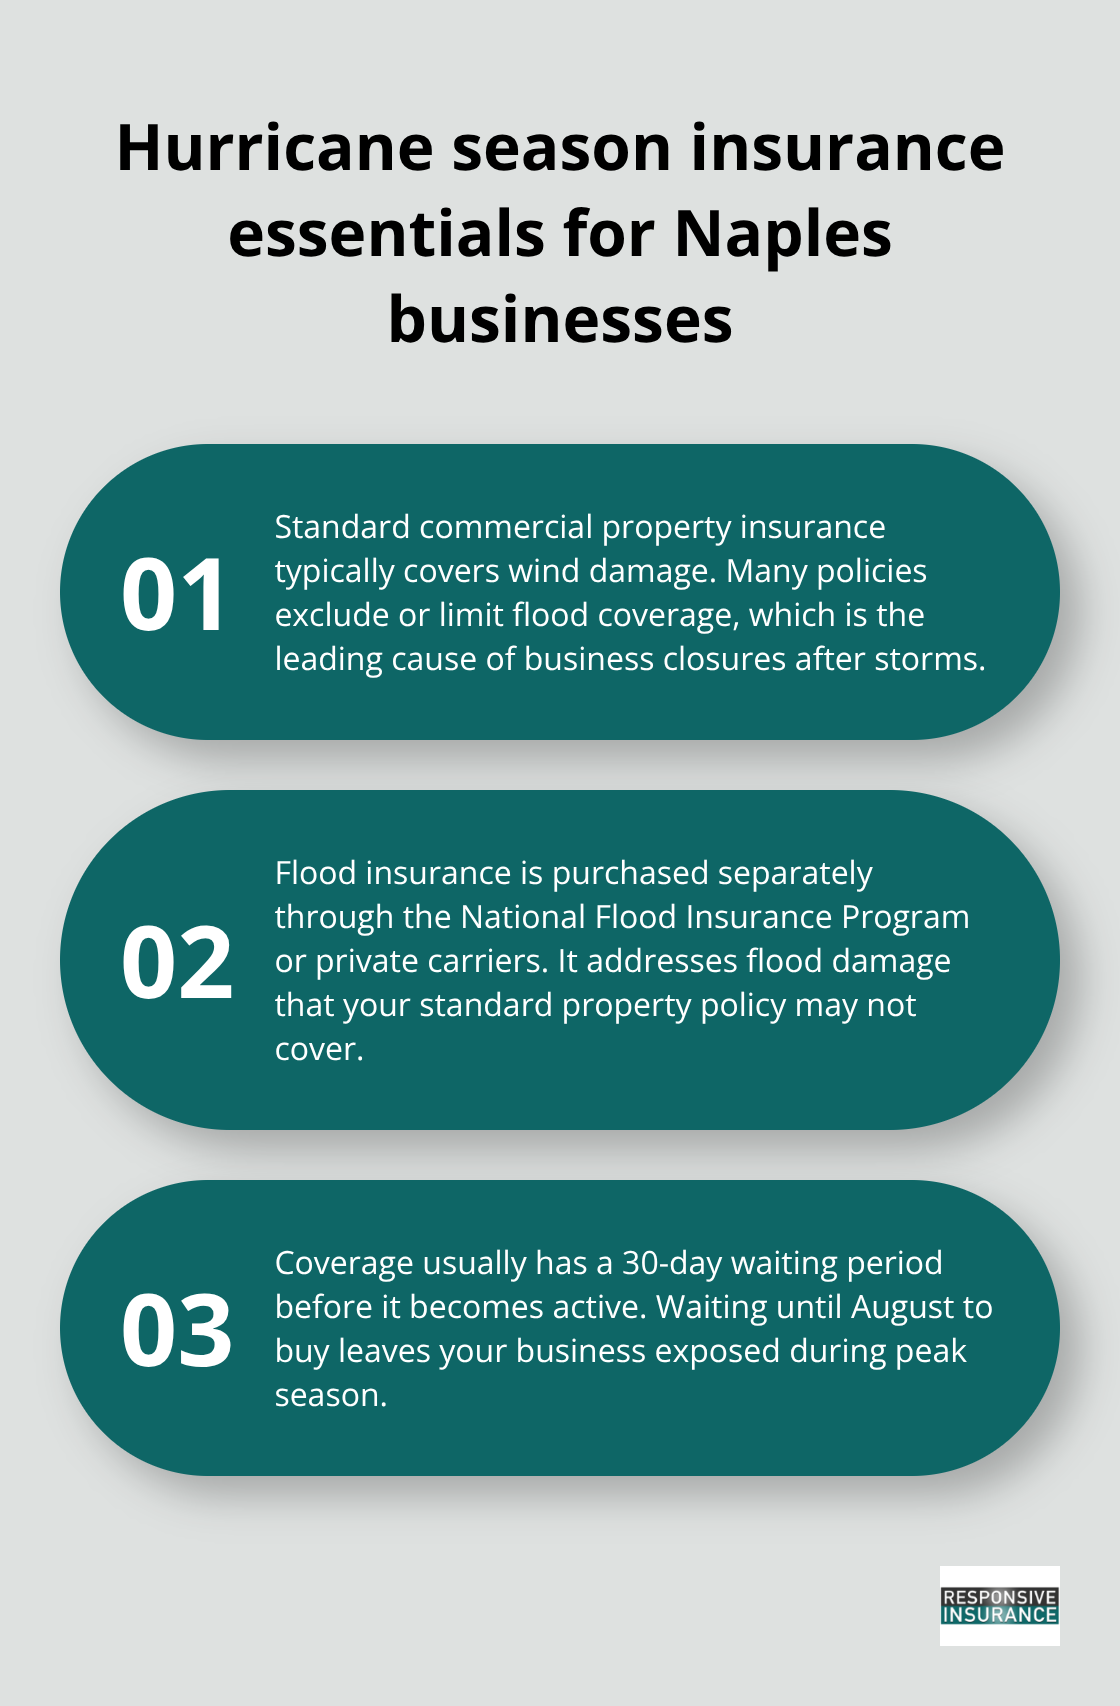
Hurricane season runs from June through November, and Southwest Florida sits directly in the strike zone. Florida has experienced 120 direct hurricane hits since 1851, with the most recent major hurricanes causing billions in damage across the region. A single hurricane destroys inventory, damages your building’s roof and walls, floods equipment, and forces your business to close for weeks or months. Standard commercial property insurance covers wind damage, but many policies exclude or limit flood coverage-the leading cause of business closures after storms. You need a separate flood insurance policy through the National Flood Insurance Program or a private carrier, and this coverage typically requires a 30-day waiting period before it becomes active. Waiting until August to purchase it leaves you exposed.
If your business operates in a flood zone, flood insurance isn’t optional.
Employee Injuries Create Hidden Liability Exposure
Employee-related incidents represent a significant hidden threat that most Naples business owners underestimate. A single serious injury claim can exceed $100,000 in medical costs and legal fees. Workers’ compensation insurance is mandatory in Florida if you have employees, but general liability coverage protects you when customers or third parties claim injuries on your property. A slip-and-fall incident, allergic reaction to a product, or accident involving your equipment can trigger claims that drain your business reserves without proper coverage. The combination of workers’ compensation and general liability insurance creates a safety net that keeps one incident from destroying your operation.
Theft and Burglary Target Naples Retailers
Theft and burglary disproportionately affect retail and service businesses in Naples, particularly during tourist season when foot traffic increases and criminals target high-value inventory. Theft is the most common property crime across Florida, with retail businesses experiencing losses averaging $2,000 to $5,000 per incident. Installing security cameras, alarm systems, and limiting cash on hand reduces risk, but your commercial property policy should include coverage for theft of merchandise, equipment, and cash. Without this protection, a break-in can devastate your finances and force temporary closure while you replace stolen goods and repair damage.
These specific threats-hurricanes, workplace injuries, and property crime-shape the insurance decisions that Naples business owners must make. Understanding what your business faces helps you identify which coverage types matter most and how much protection you actually need.
Choosing the Right Coverage for Your Naples Business
Assess Your Specific Business Risks
Start with a complete inventory of every business activity that could expose you to financial loss. Walk through your physical space, your daily operations, and your employee interactions. Do customers enter your building? Do you store inventory? Do employees drive company vehicles? Do you handle products that could cause injury? A retail shop faces different risks than a consulting firm, and a contractor’s exposure differs entirely from a salon owner’s. Write down each potential loss scenario and estimate its financial impact. This exercise sounds tedious, but it prevents you from paying for coverage you don’t need while missing gaps that could destroy your business. Most Naples business owners skip this step and end up either underinsured or overpaying for irrelevant coverage.
Compare Coverage Options Across Multiple Insurers
Contact at least three insurance providers and request detailed quotes that break down coverage limits, deductibles, and exclusions for each policy type. Don’t compare prices alone-compare what you actually get for that price. A $500-per-year general liability policy with a $1 million limit differs drastically from a $500-per-year policy with a $300,000 limit. Ask each insurer about discounts for bundling multiple policies, installing security systems, or maintaining safety records. Request quotes with identical coverage specifications so you can make true apples-to-apples comparisons. Insurance companies price risk differently based on their underwriting models, so the lowest quote isn’t always the worst value-sometimes it reflects more favorable risk assessment for your specific business type.
Partner With a Local Insurance Agent
A local insurance agent understands Southwest Florida’s particular threats and the insurance products that actually work here. They know which insurers offer competitive flood coverage in high-risk zones, which ones have strong track records processing hurricane claims quickly, and which ones overcharge for coverage you don’t need. Independent agents work with multiple A-rated insurance companies, which means they can compare options across different carriers rather than steering you toward one company’s products. Independent agents spend time understanding your business operations instead of rushing through a five-minute phone call. This matters because a misaligned policy costs you thousands when a claim happens.
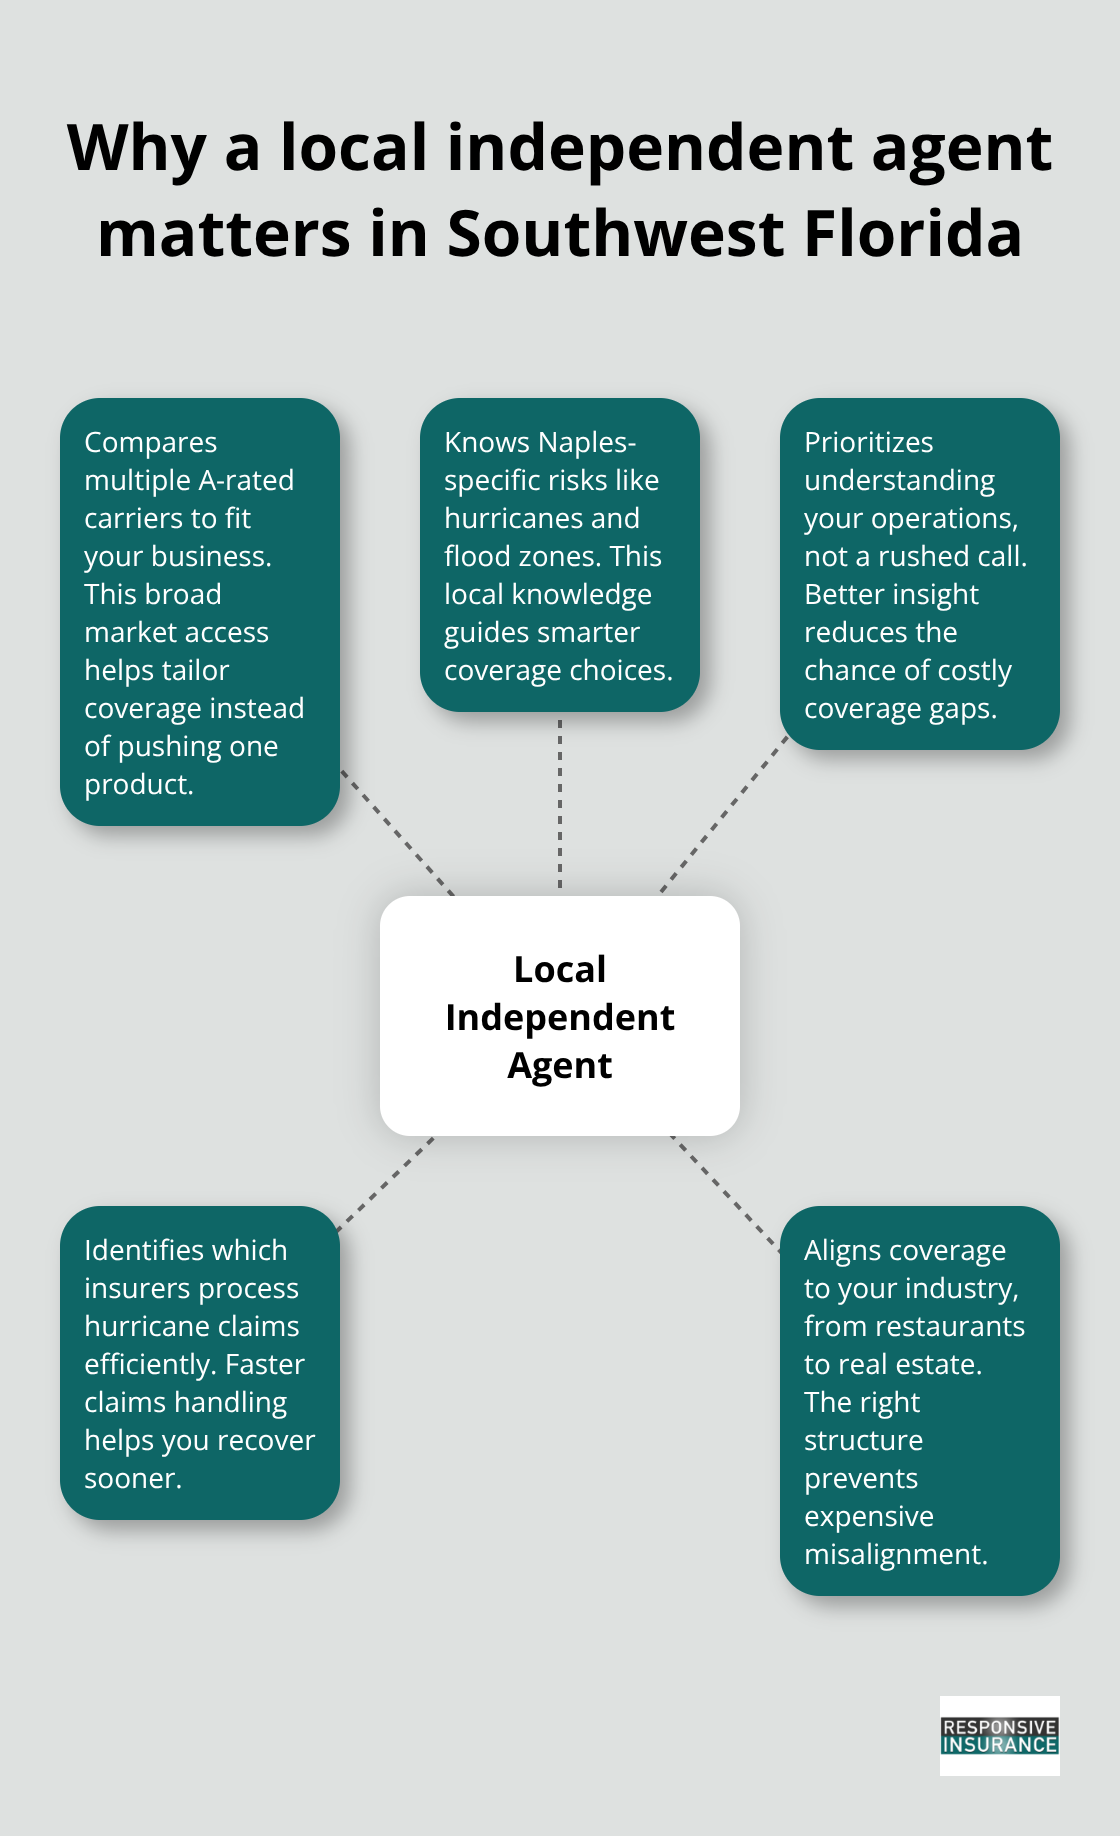
An agent familiar with Naples businesses knows that a restaurant needs different coverage than a real estate office, and they structure your protection accordingly.
Final Thoughts
Protecting your Naples business requires three foundational coverage types: general liability insurance to defend against injury claims, commercial property insurance to rebuild after damage, and commercial auto insurance for vehicles used in business operations. These three policies address the most common threats that small businesses face in Southwest Florida, from hurricane damage to slip-and-fall incidents to theft. The right Naples business insurance options depend entirely on your specific operations, industry, and risk profile.
Working with a local insurance agent transforms this process from overwhelming to manageable. An independent agent understands Southwest Florida’s particular threats, knows which insurers handle hurricane claims efficiently, and can compare coverage across multiple A-rated companies instead of pushing one carrier’s products. They spend time learning your business rather than rushing through a generic questionnaire, which matters because misaligned coverage leaves you exposed when claims happen.
Contact Responsive Insurance, Inc. to schedule a consultation where we assess your specific risks, compare coverage options, and build a protection plan that lets you focus on running your business instead of worrying about what happens when disaster strikes.


